|
FROM EQUITY RESEARCH DESK |
|
|||||||||||
|
IDEA OF THE DAY |
|
|
|
|
|
|
||||||
|
Poultry: Positive 3Q26 Earnings Momentum to Support Re-rating Despite Challenging Macro Conditions (OVERWEIGHT) · We expect the recovery in LB and DOC prices to override the impact of rising feed costs, resulting in a higher margin for the integrators. · From a soft 2Q26, we expect 3Q26 earnings to rebound by 68/67% qoq to Rp1.9tr/ Rp1.1tr for CPIN/JPFA driven by better margin. · We lift FY26-27 earnings est. by 6-11% and maintain Overweight rating given its earnings momentum. CPIN remains our top pick To see the full version of this report, please click here
Macro Strategy: Watching for the Next Signals · Curve movements remain a key BI signal as US refinancing needs continue supporting elevated global yields. · Productive credit remains strong, but declining liquidity buffers and higher money market rates tighten funding conditions. · The budget remains disciplined, but growth delivery depends more on private demand as fiscal sensitivities increase. To see the full version of this report, please click here To see the full version of this snapshoot, please click here
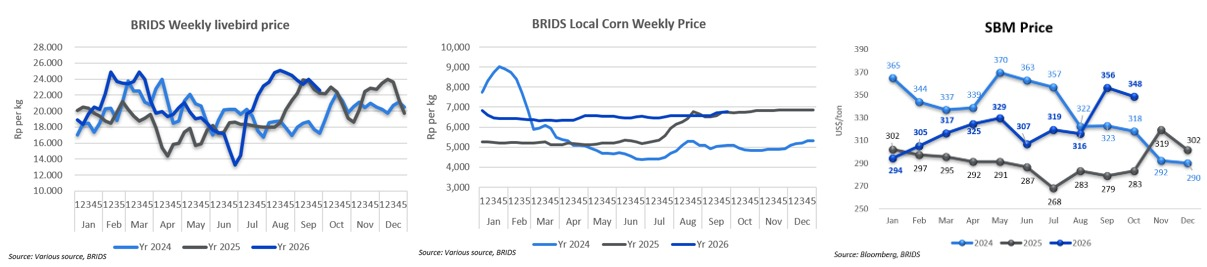
RESEARCH COMMENTARY Poultry (Overweight) – 5th Week of September 2026 Price Update · LB prices continued to normalize to Rp21.8k/kg, with the weekly average down 4% wow to Rp22.4k/kg, remaining above the estimated breakeven of ~Rp20.8k/kg. · Local corn prices continued to push higher to Rp6.8k/kg, with the weekly average up 0.8% wow at Rp6.79k/kg. · SBM prices began to ease, closing the week at US$345/t. The Sep26 average settled at US$356/t, with the MTD Oct26 average at US$348/t (-2% mom, +23% yoy). · LB prices continued to normalize this week, though the level remains above the estimated breakeven of ~Rp20.8k/kg, keeping integrator margins in positive territory. On the cost side, the pullback in SBM offers a degree of relief, though corn prices continued to rise, leaving the overall feed cost environment still elevated. Overall, integrator margins remain intact, supported by LB prices holding above breakeven despite the ongoing normalization. (Victor Stefano & Wilastita Sofi – BRIDS)
MARKET NEWS |
||||||||||||
SECTOR
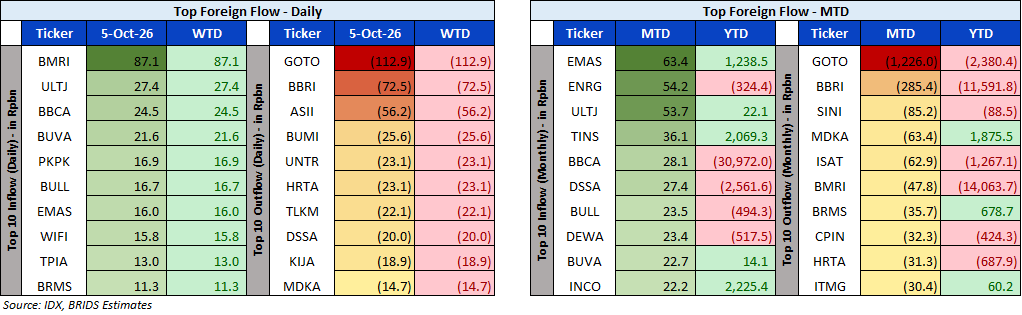
Top Foreign Flow – JCI, October 5, 2026
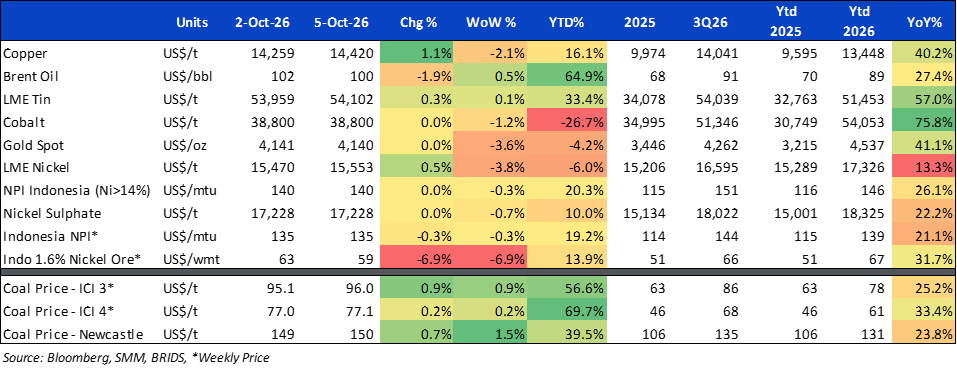
Commodity Price Daily Update October 5, 2026
CORPORATE
|
AMRT Declares Rp14.50/share Interim Dividend AMRT has declared an interim dividend of Rp14.50/share for FY26, totaling Rp595.83bn, equivalent to a 1.2% dividend yield. The dividend will be paid on 27 Oct26, with the cum-dividend date for the regular and negotiated markets on 13 Oct26 and the recording date on 15 Oct26. (Bisnis)
AUTO Declares Rp72.52/share Interim Dividend AUTO has declared an interim dividend of Rp72.52/share for FY26, totaling Rp349.55bn, equivalent to a 2.1% dividend yield. The dividend will be paid on 26 Oct26, with the cum-dividend date for the regular and negotiated markets on 13 Oct26 and the recording date on 15 Oct26. (Bisnis)
AVIA Raises FY26 Sales Growth Target to 10–14%, Builds 3rd Plant AVIA has raised its FY26 sales growth target to 10–14% from 6–10% previously, while maintaining its sales volume growth target at 4–8%. The revised target reflects two product price increases implemented in Apr and May26. AVIA is also building its third plant in Cirebon, with 1H26 expansion capex reaching around Rp112bn, mainly allocated to the new facility. (Kontan)
GMFI Secures 20-Year Concession to Operate MRO Facility in Oman GMFI has signed a 20-year Concession Agreement with Oman’s Civil Aviation Authority (CAA) to develop and operate an MRO facility at Muscat International Airport. CAA Oman will own the hangar and act as the concession provider and regulator, while GMFI will develop and operate the facility and supporting infrastructure in stages based on market demand and the agreed business plan. The facility is expected to expand GMFI’s access to the Middle East, Africa, and European markets. (Emiten News)
TPIA Sets Aside Rp266.95bn for Bond Maturity TPIA has prepared Rp266.95bn to repay the principal of its Sustainable Bonds III Chandra Asri Petrochemical Phase IV 2021 Series A, which matures on 29 Oct26. The principal and final coupon payment will be distributed through PT Kustodian Sentral Efek Indonesia (KSEI) in accordance with applicable regulations. (Emiten News)
WIKA Targets Rp5.5tr Asset Divestment by 2028 WIKA targets Rp5.5tr in asset divestments during 2026–28 to accelerate debt repayment and support financial restructuring, including Rp1.9tr in 2026 and Rp276bn in 2027. The proceeds are expected to strengthen liquidity and reduce leverage, although asset sales could lower WIKA’s recurring income. (Kontan) |