FROM EQUITY RESEARCH DESK
IDEA OF THE DAY
Macro Strategy: The Fed Tightens: Can BI Hold the Line
- The curve prices another hike, but historical patterns suggest a more measured yield adjustment than in 2022–23.
- We revisit our study on Indonesia’s three differentials, finding that policy carry provides the strongest ST buffer.
- Earlier hikes also strengthened BI’s policy buffer, allowing targeted measures to take priority rather than another rate hike.
To see the full version of this report, please click here
To see the full version of this snapshoot, please click here
RESEARCH COMMENTARY
ACES (Buy, TP Rp450) – 8M26 SSSG: Further Sequential Improvement
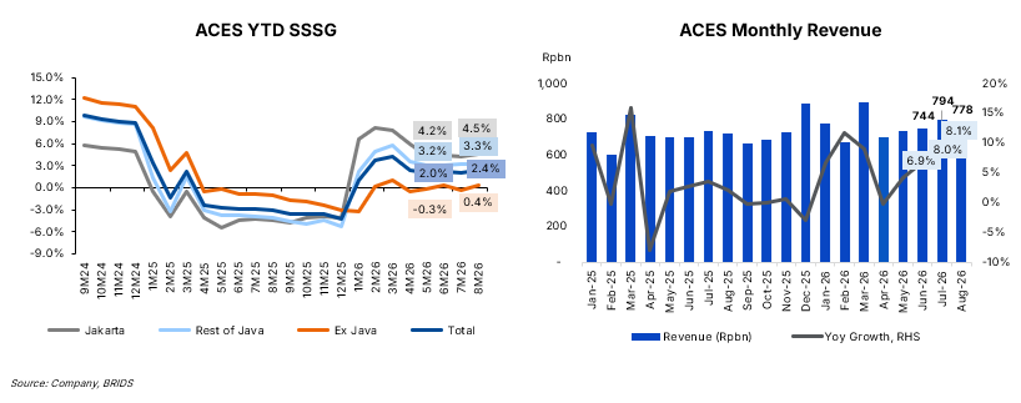
- AZKO reported indicative Aug26 sales of Rp778bn (+8.1% yoy, -2.0% mom), bringing 8M26 revenue to Rp6.1tr (+6.7% yoy) equivalent to 66.2% of our FY26F, relatively in line to our estimates.
- 8M26 SSSG reached +2.4% (vs. 7M26: +2.0%; 8M25: -3.0%), still within mgmt. target, supported by store expansion and improving SSSG across both Jakarta and ex-Java regions.
- Geographically, all regions recorded sequential improvement, with Jakarta posting SSSG of +4.5%, Rest of Java +3.3%, and Ex-Java returning to positive territory at +0.4% (vs. -0.3% in 7M26).
- These product categories (cleaning, air treatment, appliances, and outdoor comfort) became key growth contributors in Aug. (Christy Halim & Sabela Amalina – BRIDS)
AMMN (Buy, TP Rp6,000) - 1H26 Result: Strong 2Q on Higher Grades and Smelter Ramp-Up
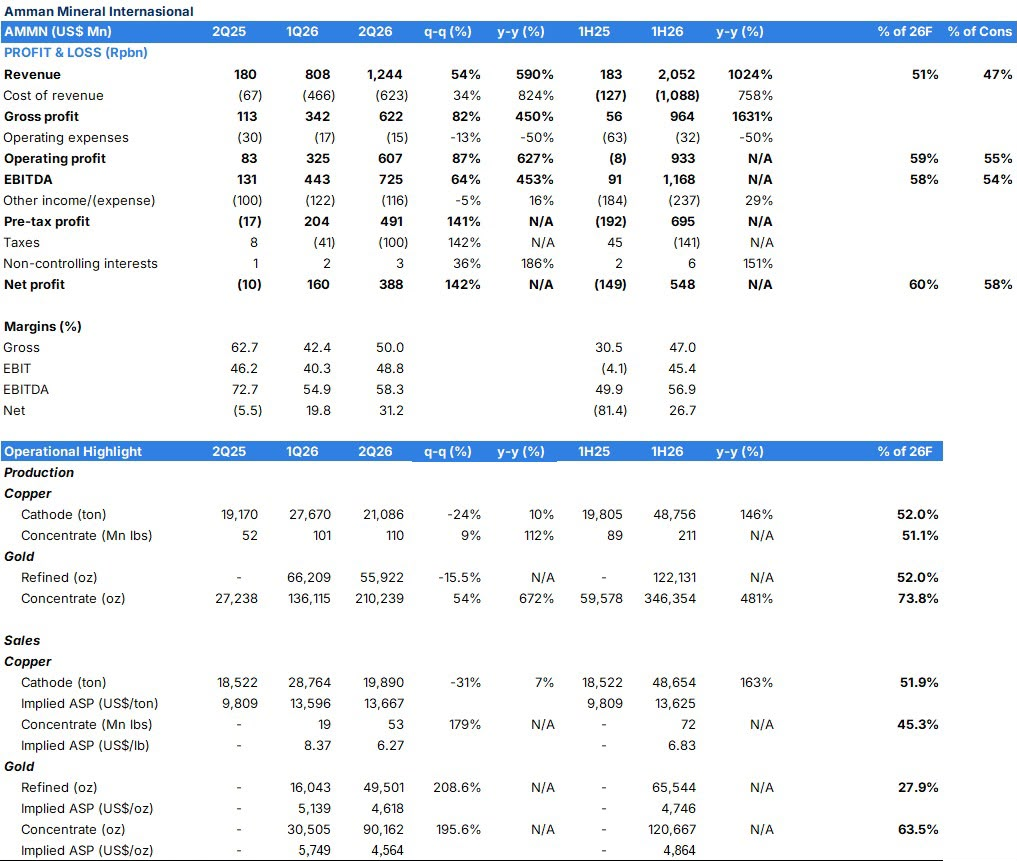
- Net profit reached US$388mn in 2Q26 (+142% q-q), bringing 1H26 net profit to US$548mn, or 60%/58% of our FY26F/consensus, slightly above both estimates.
- EBITDA rose to US$725mn (+64% q-q; +453% y-y), with margin improving to 58% from 55% in 1Q26. 1H26 EBITDA reached US$1,168mn, or 58%/54% of our FY26F/consensus, also slightly above estimates.
- Revenue reached US$1,244mn in 2Q26 (+54% q-q; +590% y-y), bringing 1H26 revenue to US$2,052mn (+1,024% y-y), broadly in line with our estimate and consensus at 51%/47%.
- Gold remained the key growth driver, with 2Q26 revenue reaching US$640mn (+148% q-q), contributing ~88% of the sequential revenue increase, as refined gold and gold concentrate sales rose 209% and 196% q-q, respectively.
- Copper revenue rose to US$604mn (+10% q-q), driven by a 179% q-q increase in concentrate sales, partly offset by a 31% decline in cathode sales. Our implied copper ASP increased 4% q-q to c.US$6.05/lb from US$5.82/lb.
- Mining performance strengthened on higher Phase 8 grades . Processed grades improved to 0.52% Cu and 0.65g/t Au (1H25: 0.33%/0.14g/t), while throughput rose 26% y-y, driving copper and gold production up 136% and 481% y-y.
- Smelter ramp-up continued to progress, with input rates reaching design capacity in Jul-Aug . Management raised FY26 gold concentrate guidance by 34% to 775koz and introduced cathode/refined gold guidance of 130kt/350koz, supported by higher grades and the fully commissioned smelter and PMR.
- 1H26 production was broadly in line with our FY26F for copper concentrate, cathode, and refined gold, while gold concentrate came in stronger at 74% of our FY26F, mainly due to higher Phase 8 mined grades. This prompted management to raise FY26 gold concentrate guidance by 34% to 775koz, while also introducing 130kt cathode and 350koz refined gold guidance as the smelter ramp-up progressed. (Andhika Audrey & Taufan Fadhillah – BRIDS)
Poultry (Overweight) – 3rd Week of September 2026 Price Update
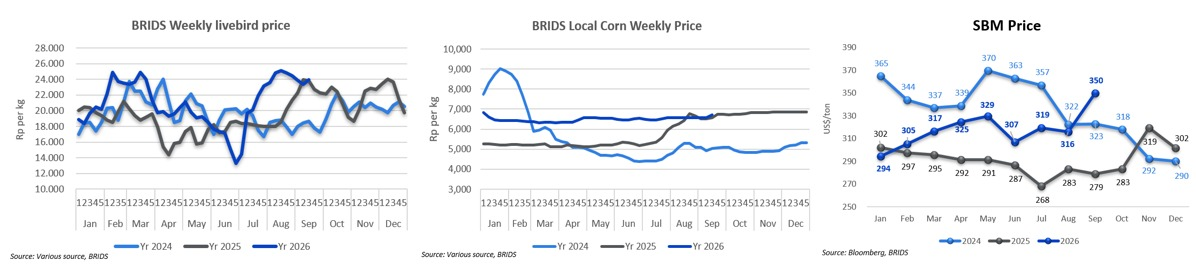
- LB prices bottomed at the low Rp23k/kg level before rebounding to Rp24.0k/kg, indicating favorable supply-demand dynamics. This lifted the weekly average by 2% wow to Rp23.9k/kg.
- Local corn prices increased to Rp6.7k/kg, bringing the weekly average up 1.8% wow to Rp6.7k/kg.
- SBM prices surged to a new YTD high of US$369/t, supported by lower-than-expected US soybean crush and heavy rains raising concerns over early harvest progress, adding to near-term SBM availability concerns. Prices closed the week at US$355/t, with the MTD Sep26 average at US$350/t (+11% mom, +25% yoy).
- The uptick in LB prices this week provides some relief, keeping prices comfortably above the estimated breakeven of ~Rp20.7k/kg. However, the cost side continues to pressure margins, with SBM reaching another YTD high and corn prices also increasing this week, adding further pressure to feed costs. Overall, despite rising feed costs, we believe integrator margins remain solid, supported by LB prices remaining well above breakeven. (Victor Stefano & Wilastita Sofi – BRIDS)
MARKET NEWS
SECTOR
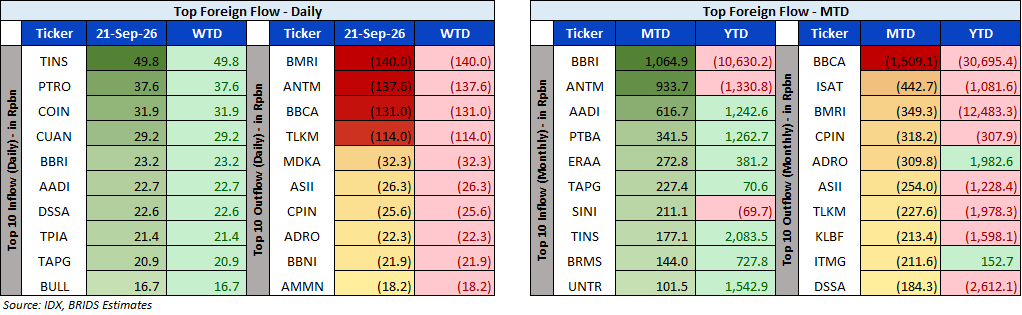
Top Foreign Flow – JCI, September 21, 2026
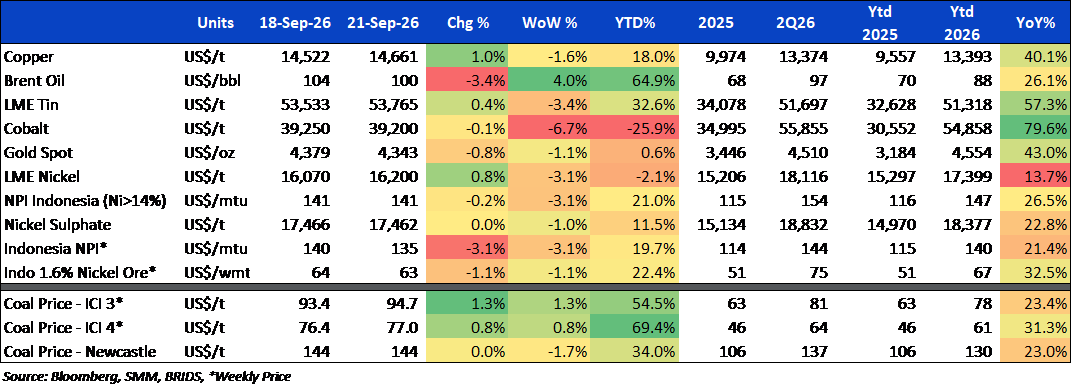
Commodity Price Daily Update September 21, 2026
CORPORATE
BYAN Subsidiaries Secure Additional 15-20mn Ton Coal Production Quota
BYAN subsidiaries PT Tiwa Abadi, PT Tanur Jaya, and PT Fajar Sakti Prima received approval for additional coal production quotas totaling about 15-20mn tons under a revised RKAB 2026. The RKAB revision was unrelated to any shareholder or corporate action changes, adding that any shareholder change at mining companies requires ministerial approval to be valid. (Bisnis)
JSMR Injects Rp6.54tr Shareholder Loan Into JJC via JTT
JSMR subsidiary Jasamarga Transjawa Tol (JTT) provided a Rp6.54tr shareholder loan (SHL) to Jasamarga Jalanlayang Cikampek (JJC), with the transaction notarized September 17, 2026. The loan, deemed fair per appraisal by KJPP Budi, Edy, Saptono & Rekan dated September 15, 2026, will fund JJC's 2026 bridging refinancing and other operational needs, reducing cash and equivalents while increasing other receivables by Rp6.54tr, with no impact on consolidated pro forma revenue or expenses. (Emiten News)
PGEO Drills Second Well for 55MW Lumut Balai Unit 3 Geothermal Plant
PGEO began drilling its second well, LMB-19.4, on September 17, 2026, targeted for completion in 40 days as part of the 55MW Lumut Balai Unit 3 geothermal plant development, using rig GDAP#123. The project in South Sumatra targets full commercial operation by 2030, supporting PGE's capacity targets of 1GW by 2028 and 1.8GW by 2034. (Kontan)