|
FROM EQUITY RESEARCH DESK |
|
|||||||||||
|
IDEA OF THE DAY |
|
|
|
|
|
|
||||||
|
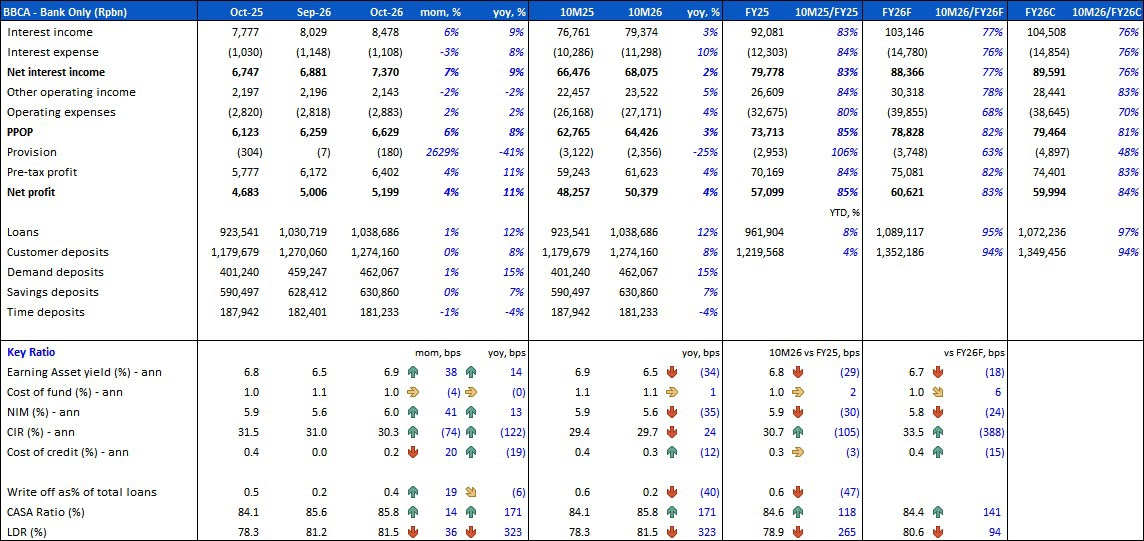
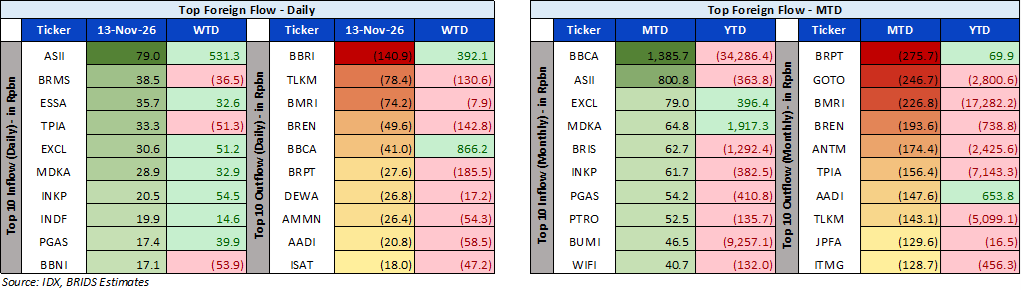
RESEARCH COMMENTARY BBCA (Buy, TP Rp8,600) – Oct26 Results (Bank-only) Oct26 Insights: · Net profit up 11% yoy on stronger NII: BBCA posted net profit of Rp5.2tr in Oct26 (+4% mom, +11% yoy). Strong NII growth and lower provisions more than offset softer non-II. · NIM up 41bps mom on higher yield and lower CoF: NII grew 7% mom/9% yoy to Rp7.4tr, as NIM improved to 6% (+41bps mom, +13bps yoy), driven by a 38bps mom rise in EA yield to 6.9% (+14bps yoy), while CoF eased 4bps mom to 1.0%. · PPOP grew on stronger NII: PPOP rose 6% mom/8% yoy to Rp6.6tr, supported by strong NII growth, offsetting a 2% mom/yoy decline in non-interest income and a 2% mom/yoy rise in opex, bringing CIR down to 30.3% (-74bps mom, -122bps yoy). · CoC stayed low despite mom rise: Provisions rose to Rp180bn from Sep26's unusually low provision, but were still 41% lower yoy. CoC stood at 0.2% (+20bps mom, -19bps yoy), while write-offs rose to 0.4% of loans (+19bps mom, -6bps yoy). · Loans outpacing deposits, with LDR at a four-year high: Loans rose by Rp8.0tr to Rp1,039tr (+1% mom, +12% yoy), nearly double the Rp4.1tr increase in deposits to Rp1,274tr (flat mom, +8% yoy). LDR rose to 81.5% (+36bps mom, +323bps yoy), its highest level in four years. · Stronger CASA mix: CASA ratio improved to 85.8% (+14bps mom, +171bps yoy), also the highest since 2022, as demand deposits grew 1% mom/15% yoy while time deposits fell 1% mom/4% yoy. 10M26 Insights: · Bottom line up 4% yoy, in line: BBCA booked net profit of Rp50.4tr in 10M26 (+4% yoy), reaching 83% of our FY26F and 84% of consensus, broadly in line. · Loan growth offsetting lower NIM: NII grew 2% yoy to Rp68.1tr, as 12% yoy loan growth offset a 35bps yoy decline in NIM to 5.6%. EA yield fell 34bps yoy to 6.5%, while CoF stayed flat at 1.1%. · PPOP up 3% yoy on NII and non-II: PPOP grew 3% yoy to Rp64.4tr, as NII (+2% yoy) and non-II (+5% yoy) offset a 4% yoy rise in opex. CIR rose 24bps yoy to 29.7%. · Benign credit cost, below guidance: Provisions fell 25% yoy to Rp2.4tr, bringing CoC down to 0.3% (-12bps yoy), below management's 40-60bps CoC guidance. Summary: · Overall performance: We view BBCA's Oct26 results as solid. NIM rose to 6.0% on higher EA yield and lower CoF, loan growth remained strong, and credit cost stayed contained. In our view, the key watchout is NIM sustainability. Oct26 NIM is already well above the 10M26 average of 5.6%, with further repricing likely to be harder as SOE banks push loan growth, while an LDR at a four-year high may require more deposit funding and put pressure on CoF. (Victor Stefano & Nataniella Eva Kezia– BRIDS)
· Poultry (Overweight) – Corn HAP Enforcement Opens Room for Feed Margin Recovery · Bapanas issued SE No. 457/2026 (10 Nov), a day after the 29% LB rebound we flagged on 9 Nov. This confirms our view that the jump was policy-driven. The circular makes reference prices (HAP) for food staples, including chicken and corn, enforceable. Breaches carry administrative sanctions (warnings, fines, licence revocation) and criminal sanctions of up to 7 years' jail and a Rp1.5bn fine. · Enforcement is notably tougher this time. Supervisors now include police and military regional commanders (Kapolda, Pangdam, Kapolres, Dandim), alongside Bapanas and regional heads. Violations are referred directly to law enforcement. · Key poultry reference prices: o LB (farm gate): Rp25.0k/kg; chicken meat (consumer): Rp40.0k/kg o DOC broiler: Rp6.5–7.0k/chick o Eggs: Rp26.5k/kg (farm gate); Rp30.0k/kg (consumer) o Corn (farmer, 15% moisture): Rp5.8k/kg
· Corn HAP is the bigger story. If corn falls to Rp5.8k/kg, our LB BEP estimate drops sharply to ~Rp19.5k/kg (from ~Rp22.1k). The current LB price of Rp22.0k would then sit ~13% above BEP, and the Rp25.0k HAP would be ~28% above. · Feed margin recovery. The wide gap between LB prices and production cost gives feedmills room to keep feed prices largely intact while input costs fall. That should translate into higher feed margins, which have been compressed over the past few years by elevated local corn prices and changes in import policy. Based on our channel checks, some feedmills will start implementing this as of today (Fri, 13 Nov). · Among integrators under our coverage, MAIN would be the most benefitted due to its higher feedmill contribution, although both CPIN and JPFA would also be significantly affected. · Key risks: Downstream squeeze. At Rp25k LB, carcass cost is ~Rp35k/kg before processing and distribution, leaving a thin margin under the Rp40k consumer HAP. Together with bakul pushback, this risks weaker offtake. (Victor Stefano & Wilastita – BRIDS)
MARKET NEWS |
||||||||||||
MACROECONOMY
|
Indonesia’s Fiscal Deficit Stood At 1.47% Of GDP As of Oct26 Indonesia’s fiscal deficit stood at 1.47% of GDP as of Oct26, compared with 2.01% a year earlier. State revenue surged 23.9% yoy to Rp2,618.0tr, supported by stronger tax receipts (+23.2%) and non-tax revenue (+37.0%). Meanwhile, government spending rose 15.6% to Rp2,997.2tr, driven by central government expenditure (+24.7%), particularly goods spending (+58.1%). Capital spending also increased 20.4%, while regional transfers contracted 8.4%. Net debt financing reached Rp629.3tr, including Rp586.1tr from government securities. (MoF)
US Producer Prices Rose 0.3% mom In Oct26 US producer prices rose 0.3% mom in Oct26, below expectations of 0.4%, as goods and services inflation moderated. Core PPI also increased 0.3%, while prices excluding food, energy, and trade services rose 0.5%. However, annual headline PPI accelerated to 6.5%, its highest since November 2022, while core inflation remained elevated at 5.0%. Persistent inflation pressures reinforce expectations of a potential Fed rate hike in December. (CNBC) |
SECTOR
|
Top Foreign Flow – JCI, November 13,2026 |
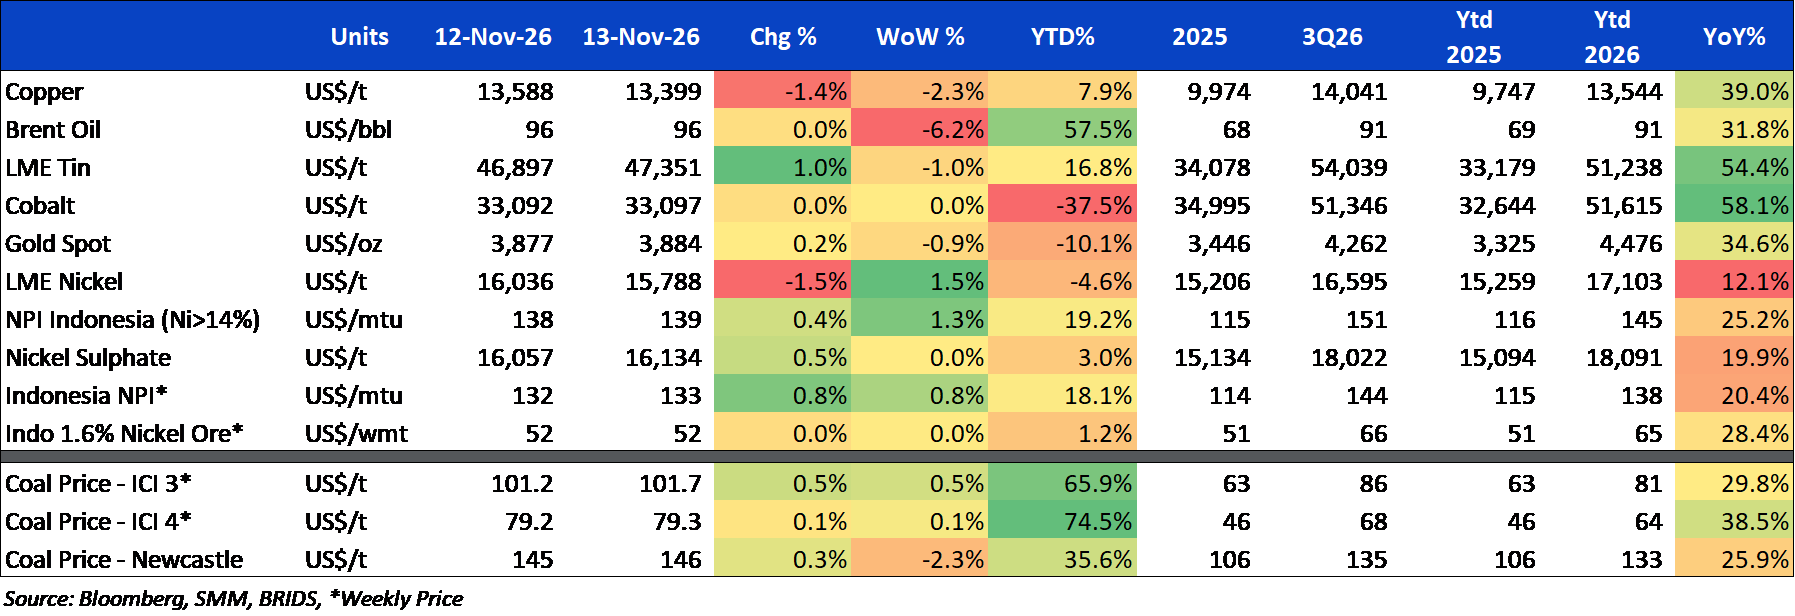
Commodity Price Daily Update November 13,2026
CORPORATE
|
BBKP Completes 85% Stake Sale in KBBF to JB Woori Capital for Rp340bn BBKP completed the divestment of its 85% stake in PT kb Bukopin Finance (KBBF) to JB Woori Capital on 4 November 2026, with the Rp340bn transaction value set based on due diligence and negotiation. BBKP retains a 14.24% stake with a three-year lock-up. BBKP holds a put option on the remaining shares, while JB Woori Capital holds a call option, both based on a formula agreed in the agreement. (Kontan)
GMFI Plans Rp1.05tr Rights Issue GMFI plans a rights issue to raise up to US$59.4mn (Rp1.05 trillion) to support business expansion, equipment upgrades, and working capital. If fully subscribed, the proceeds are expected to strengthen liquidity, restore positive equity, and improve financial ratios, although non-participating shareholders may face up to 15% dilution. (Bisnis)
MEDC Announces Rp22.03 Interim Dividend per Share MEDC has declared a US$30mn interim dividend for 2026, equivalent to Rp22.03 per share for Indonesian shareholders. The dividend payment is scheduled for December 2, 2026, with eligible shareholders recorded as of November 12, 2026. (Emiten News)
MEDC Prepares Seismic Exploration in Two New Oil and Gas Blocks MEDC is preparing seismic activities in two new blocks, Amanah in South Sumatra and Nawasena in East Java, as part of its strategy to sustain long-term growth. Nawasena, about 7,031 sq km, was obtained from the ESDM Ministry on 20 May 2026 via subsidiary PT Medco Energi Nawasena under a PSC cost recovery scheme. Amanah, at 1,753.15 sq km, is held via PT Medco Energi Linggau, has oil and gas reserve potential, and lies near Medco E&P’s producing blocks. (Investor Daily)
PGEO Explores Geothermal Energy Supply for Data Centers PGEO is exploring opportunities to supply clean geothermal energy to Indonesia’s data center industry through collaborations with Lintasarta, IDPRO, and the University of Indonesia. The initiative aims to support AI development, strengthen digital infrastructure, and expand geothermal energy utilization beyond electricity generation. (Emiten News)
ULTJ Announces Dividend and Plans Frisian Flag Acquisition ULTJ approved a Rp1.03tr cash dividend (Rp100 per share) and a rights issue of up to 10 billion shares to finance its planned acquisition of 100% ownership of PT Frisian Flag Indonesia. Approved at an Extraordinary General Meeting on November 6, 2026, the acquisition involves 24,440 shares from three existing shareholders and remains subject to applicable regulatory requirements. (Bisnis) |
To see the full version of this snapshoot, please click here