FROM EQUITY RESEARCH DESK
IDEA OF THE DAY
Timah: Onshore Recovery Lifts 3Q26 Earnings; Belitung Site Visit Confirms Permits as Key Volume Risk (TINS.IJ Rp3,390; BUY TP Rp5,000)
- TINS’ Belitung ore output reached ~10kt (vs. 1.5kt prev), supported by partner mining, with above-quota prod. permitted until Aug27.
- We raise FY26F/27F/28F net profit est. by 16.1%/8.6%/8.4% on cost efficiency, despite lower ASP and sales volume assumptions.
- Maintain Buy rating with higher TP of Rp5,000, supported by tight tin supply and improving earnings outlook.
To see the full version of this report, please click here
To see the full version of this snapshoot, please click here
RESEARCH COMMENTARY
BMRI (Buy, TP Rp6,400) – Oct26 Results (Bank-only)
Oct26 Insights:
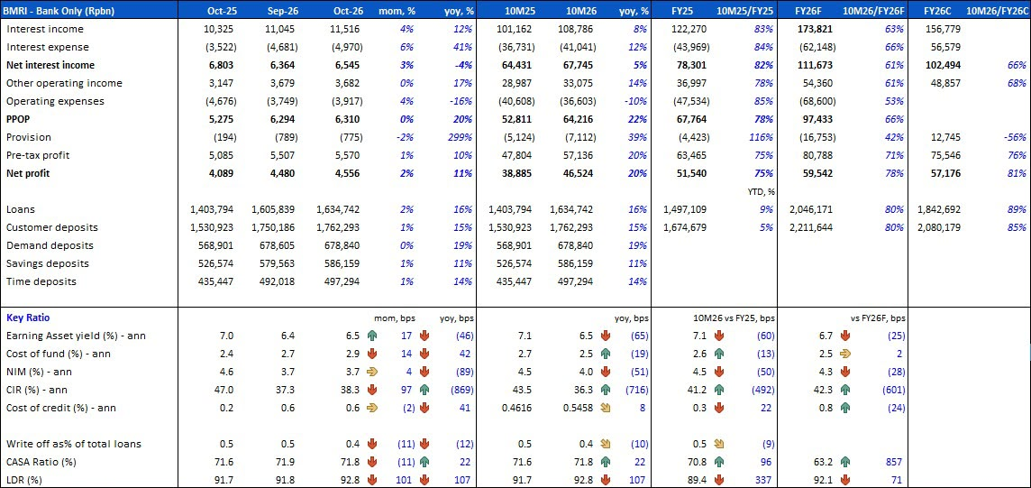
- Net profit up 11% yoy on stronger PPOP: BMRI posted net profit of Rp4.6tr in Oct26 (+2% mom, +11% yoy). Contained opex and higher non-II more than offset weaker NII and higher provisions.
- NIM broadly flat mom, but CoF still rising: NII rose 3% mom, helped by October’s extra day, but fell 4% yoy to Rp6.5tr. NIM was broadly flat mom at 3.7% (+4bps) but down 89bps yoy, as EA yield fell 46bps yoy to 6.5% and CoF rose 42bps yoy (+14bps mom) to 2.9%. With CASA broadly stable, the CoF increase looks rate-driven rather than mix-driven.
- PPOP up 20% yoy on lower opex and higher non-II: PPOP was flat mom at Rp6.3tr but up 20% yoy, as non-II grew 17% yoy (flat mom) and opex fell 16% yoy. A 4% mom rise in opex lifted CIR 97bps mom to 38.3%, though it is still 869bps lower yoy.
- Provisions up yoy from a low Oct25 base: Provisions eased 2% mom to Rp775bn but were nearly 4x Oct25’s unusually low Rp194bn. CoC was broadly flat mom at 0.6% (-2bps mom, +41bps yoy), while write-offs eased to 0.4% of loans (-11bps mom).
- Loans outpacing deposits: Loans rose by Rp28.9tr to Rp1,635tr (+2% mom, +16% yoy), more than double the Rp12.1tr deposit inflow (+1% mom, +15% yoy, to Rp1,762tr). LDR rose to 92.8% (+101bps mom, +107bps yoy). CASA eased slightly to 71.8% (-11bps mom, +22bps yoy) as demand deposits were flat.
10M26 Insights:
- Bottom line up 20% yoy, ahead of consensus: BMRI booked net profit of Rp46.5tr in 10M26 (+20% yoy), reaching 78% of our FY26F and 81% of consensus (10M25: 69% of FY25). This is broadly ahead because of the Dec25’s NP spike.
- Loan growth offsetting lower NIM: NII grew 5% yoy to Rp67.7tr, as 16% yoy loan growth offset a 51bps yoy decline in NIM to 4.0%. EA yield fell 65bps yoy to 6.5%, only partly cushioned by a 19bps yoy decline in CoF to 2.5%.
- Broad-based PPOP growth: PPOP grew 22% yoy to Rp64.2tr. The Rp11.4tr increase came roughly equally from NII, non-II (+14% yoy) and lower opex (-10% yoy). CIR fell 716bps yoy to 36.3%.
- CoC remained contained: Provisions rose 39% yoy to Rp7.1tr, but CoC rose only 8bps yoy to 0.55%, below management’s 0.6-0.8% full-year guidance. Write-offs eased to 0.4% of loans (-10bps yoy).
Summary:
- Overall performance: We view BMRI’s Oct26 results as Neutral as the strong loan growth, lower opex and higher non-II was offset by NIM compression. The steep yoy jump in Oct26 provisions mainly reflects a low Oct25 base, and cumulative CoC remains benign. Key watchout – NIM: Oct26 NIM of 3.7% and CoF of 2.9% compare with 10M26 averages of 4.0% and 2.5%. With LDR at 92.8%, there is limited room to ease deposit pricing, so margin pressure is likely to carry into year-end. (Victor Stefano & Nataniella Eva Kezia – BRIDS)
MARKET NEWS
MACROECONOMY
|
Indonesia’s Adjusted Reserve Money (M0) Grew By 7.0% yoy In Oct26 Indonesia’s adjusted reserve money (M0) grew by 7.0% yoy in October 2026, slowing from 9.3% in September, to reach IDR2,265.4tn. The moderation was mainly driven by a deceleration in currency in circulation, which grew by 11.5% YoY, while adjusted commercial bank deposits at Bank Indonesia contracted by 2.4%. The adjusted M0 measure already accounts for the impact of liquidity incentives provided by Bank Indonesia through its monetary control operations. The slower growth suggests a moderation in reserve money expansion, although currency in circulation continued to provide support. (Bank Indonesia)
US Nonfarm Payrolls Rose By 165K In Oct26 |
US nonfarm payrolls rose by 165K in Oct26, accelerating from an upwardly revised 60K in September and significantly exceeding market expectations of 59K. The unemployment rate edged down to 4.1%, below the anticipated 4.2%, while the broader underemployment rate increased to 7.9%. Job gains were led by professional and business services (+70K), healthcare (+42K), and transportation and warehousing (+25K). Manufacturing added 19K jobs, extending its recovery. Meanwhile, August and September payroll figures were revised upward by a combined 84K, reinforcing signs of labor market resilience. (CNBC)
SECTOR
|
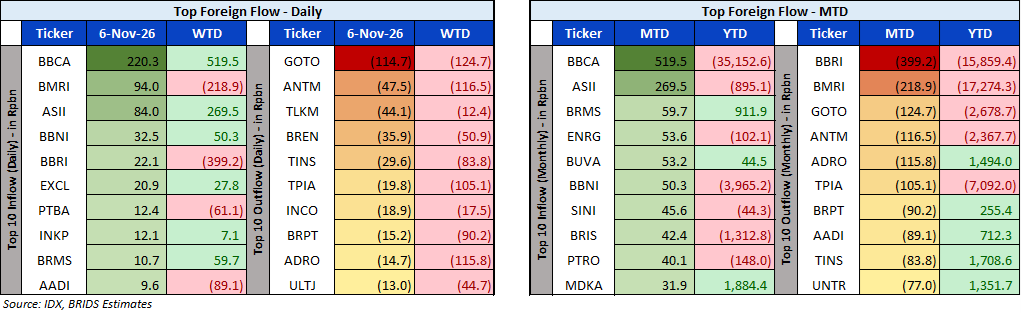
Top Foreign Flow – JCI, November 6,2026 |
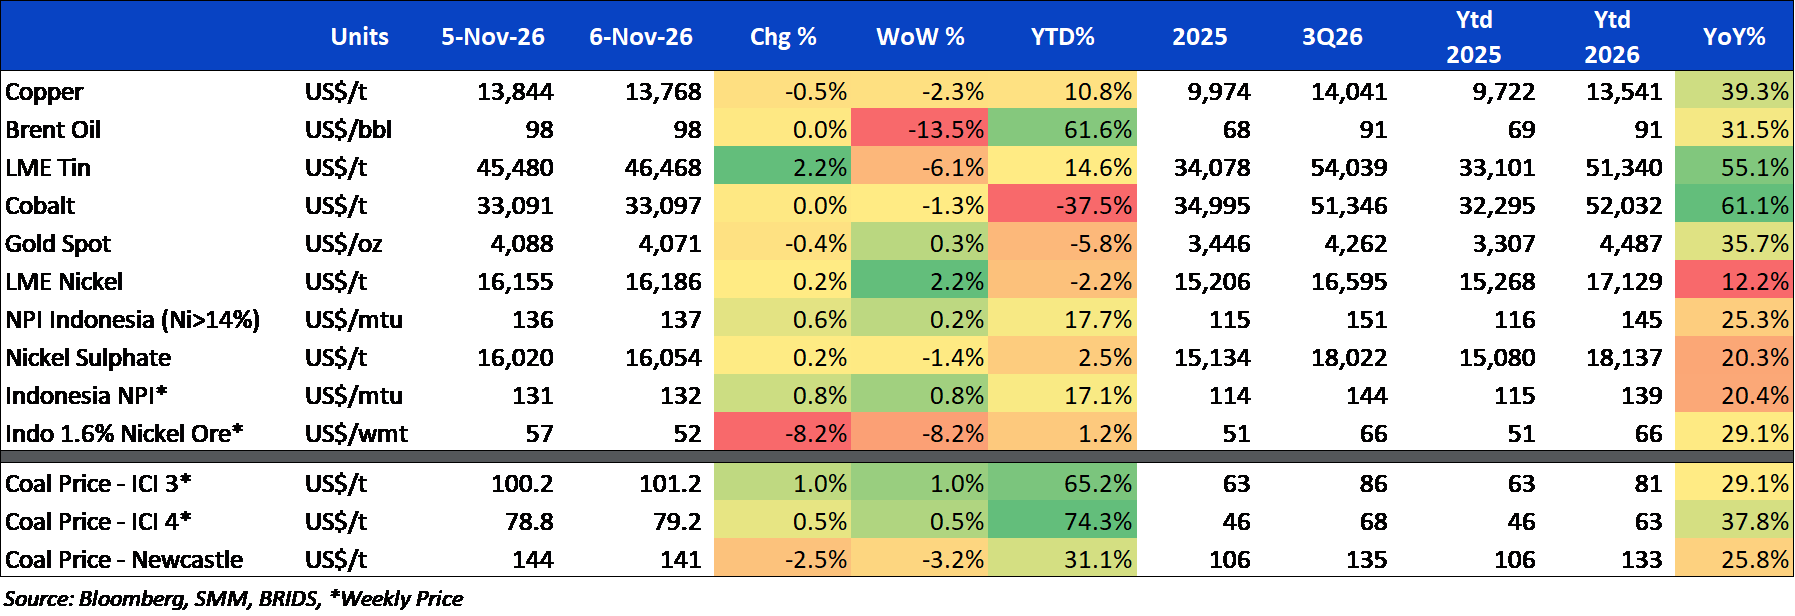
Commodity Price Daily Update November 6, 2026
Indonesia’s Food and Beverage Industry Targets Over 6% Growth in 2026
Indonesia’s food and beverage industry (GAPMMI) is projected to grow by over 6% in 2026, supported by resilient consumer demand and strong performance in subsectors such as seasonings, bottled water, and frozen food. However, rising production costs, imported raw material prices, rupiah volatility, and higher logistics expenses may pressure profit margins and drive average product price increases of 5%–6% in early 2027. (Kontan)
CORPORATE
|
BRIS Launches Rp2tr Sustainability-Linked Sukuk Offering BRIS is offering Rp2tr in Phase III of its Sustainability-Based Mudharabah Sukuk I 2026, as part of a Rp10 tr continuous offering program, with an AAA (Syariah) rating from Pefindo. The sukuk consists of three series with maturities of 370 days, two years, and three years, offering indicative returns of 7.00%, 7.05%, and 7.20% per annum, respectively. (Emiten News)
MEDC Issues US$300mn Bonds Due 2032 MEDC, through its subsidiary Medco Redwood Tree Limited, successfully issued US$300 million of bonds due in 2032, carrying an 8.875% coupon and guaranteed by the parent company. The net proceeds will be used to refinance or repay existing debt, supporting the company’s proactive liability management and financial discipline. Separately, MEDC approved an interim dividend of US$30 million for FY2026, with payment scheduled no later than December 2, 2026. (Bisnis)
ROTI Plans to Withdraw 8.31% of Treasury Shares ROTI plans to withdraw 514.21 million treasury shares, equivalent to 8.31% of its issued capital, through a capital reduction, subject to shareholder approval at the EGMS on December 15, 2026. (Emiten News)
TOTL Announces Rp40/Share Interim Dividend TOTL plans to distribute an interim dividend of Rp136.4bn, equivalent to Rp40 per share, for FY26, representing a 30.4% payout ratio against 9M26 net profit of Rp448.6bn. Based on the latest share price of Rp1,385, the dividend implies a 2.9% yield. (Emiten News) |