BRIDS Market Pulse
In the Spotlight
Market and Sector Performance. JCI rose 1.82% w-w to 6,636.48, with the rupiah strengthening in tandem to Rp17,642/US$ (+0.57% w-w). Regionally, Indonesia's gain (+1.8%) matched Singapore and trailed only the Philippines (+2.3%); Japan (-2.1%), Korea (-1.5%) and Malaysia/India (-1.0% each). By IDX sector, Industrials led at +6.5%, followed by Energy (+4.5%), Technology (+4.0%), Financials (+3.2%) and Transportation & Logistics (+3.1%); Basic Material and Healthcare were the only sectors in the red, both -1.3%. By index points, BBRI (+29.4pts), BBCA (+22.2pts) and BMRI (+14.0pts) were the three largest contributors, with BUMI (+7.4pts). Across BRIDS coverage, Technology led at +13.7% w-w, followed by Cement (+7.5%), Coal (+6.5%) and Oil & Gas (+5.9%); Consumer (-4.4%), Retail (-3.1%) and Metal (-2.7%) were the weakest.
Banks Supply the Leadership, Metals Give Some Back. All four large-cap banks ranked among the week's top ten index-point contributors, with BBRI, BBCA and BMRI alone contributing roughly 65 points. The rally coincided with Destry Damayanti's swearing-in as BI Governor on 2-Sep, and her explicit stability-first, policy-continuity messaging appears to have reassured the market ahead of banks' typically rate-sensitive positioning. The gold- and copper-linked miners (EMAS, BRMS, MDKA) were among this week's largest point detractors as gold pulled back from its August highs.
Foreign Flows
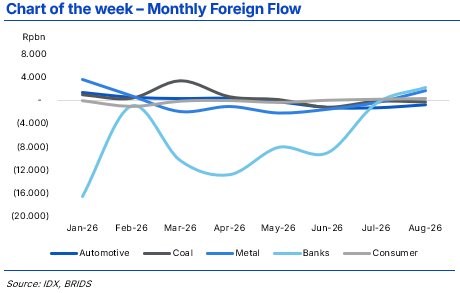
Indonesia recorded a WTD inflow of US$130.0mn as of 4-Sep, similar in scale to the prior fortnight's smaller positive prints. Brazil led with US$518.3mn, while India (US$782.2mn), Taiwan (US$2.41bn) and South Korea (US$1.85bn) saw the largest outflows. On a YTD basis, Indonesia's cumulative foreign outflow narrowed further to US$3.94bn from US$4.08bn as of 21-Aug (exh. 3).
Foreign buying in the regular market this week was led by BBRI (Rp1,444.5bn), BBCA (Rp822.3bn) and BMRI (Rp692.2bn), with BBNI, TINS, CUAN and AADI also drawing solid inflows. Selling was concentrated in CPIN (Rp512.8bn) despite the stock's 4.9% gain, followed by EMAS (Rp239.3bn), ASII (Rp194.2bn) and ISAT (Rp185.6bn).
Index Movers
BBRI was the dominant single contributor this week, adding 29.4 index points on a 6.27% gain, with BBCA (+22.2pts) and BMRI (+14.0pts) close behind. BUMI added 7.4 points on a 10.53% gain, while small-cap Olympus Strategic Indonesia surged 84.67% to add 7.0 points, and BELI (+6.65pts, +33.85%) and CUAN (+6.28pts, +16.05%) also featured prominently.
On the downside, BYAN was the largest drag, removing 12.7 points on a 5.32% decline, followed by VKTR (-6.2pts, -10.36%), EMAS (-5.9pts, -6.72%), BRMS (-5.2pts, -4.67%) and SRAJ (-5.2pts, -7.64%). MDKA, Ekamas Mora Republik, ICBP, BRPT and MBMA rounded out the detractor list.
Sector and Coverage Performance
By IDX sector, Industrials led at +6.5%, followed by Energy at +4.5%, Technology at +4.0%, Financials at +3.2%, Transportation & Logistics at +3.1%, Consumer Cyclical at +2.2%, Properties and Real Estate at +2.0%, Consumer Non-Cyclical at +1.5% and Infrastructure at +0.1%. Basic Material and Healthcare were the only sectors in negative territory, both down 1.3%.
Across BRIDS coverage, Technology led at +13.7%, driven by the GOTO/BUKA-led tech rally, followed by Cement (+7.5%), Coal (+6.5%) and Oil and Gas (+5.9%); Infrastructure, Poultry, Banks and Heavy Equipment also outperformed. Consumer was the weakest sector at -4.4%, followed by Retail (-3.1%) and Metal (-2.7%), the latter giving back part of the prior rally as gold retreated.
Indonesia Policy and Macro
- Destry Damayanti was sworn in as BI Governor on 2-Sep, alongside Aida S. Budiman as Senior Deputy Governor and Solikin M. Juhro as Deputy Governor, all for 2026-2031 terms, following DPR confirmation on 1-Sep and Perry Warjiyo's resignation on 25-Jul. Destry's message was explicitly continuity-focused: stability remains the first priority, with the calibration between pro-stability and pro-growth instruments to be data-dependent. We read this as reinforcing the targeted-incentive (SRBI/macroprudential) approach rather than signaling any near-term rate move. The next RDG is scheduled for 22-23 Sep, Destry's first as confirmed Governor, and consensus expects a hold at 5.75%.
- August CPI accelerated to 3.19% y-y (core 2.92% y-y), driven by food, beverages and tobacco (+3.86% y-y, contributing 1.13ppt) alongside gold jewelry and transport costs; the print remains within BI's 2.5%±1% target corridor. Manufacturing PMI slipped back into contraction at 49.8 in August from July's 50.2, with output and employment both declining, though business confidence hit a seven-month high.
- July's trade balance posted a US$120mn surplus, reversing June's US$450mn deficit and May's US$1.61bn deficit, Indonesia's first deficit since April 2020, with the Trade Ministry attributing the May-June pressure to the Middle East-driven oil price spike. The 10Y SBN yield eased to 7.10% on 3-Sep down 13bps on the day and 26bps over the past month.
War Watch
Iran struck Kuwait with missiles and drones on 3-Sep, with attacks also reported against US interests in Bahrain and Jordan, retaliating for US strikes on IRGC targets on 1-Sep. President Trump warned of a stronger response should Iran continue, while reports suggest his aides are seeking to contain the conflict ahead of November's midterms. The escalation kept Brent bid, extending the fuel-subsidy and inflation risk to Indonesia's policy calculus.
Global
US August nonfarm payrolls surprised sharply to the upside at +162k versus expectations of roughly 45-55k, with unemployment steady at 4.1% and July revised from negative to positive. The 10Y UST yield jumped toward the 4.8% resistance zone (near January-2025 highs) on the print, lifting September rate-hike odds. Gold had firmed earlier in the week on a softer ADP read before reversing on the NFP surprise. Notably, the AI/tech trade held up domestically.
Commodities
Thermal coal firmed sharply, with ICI-3 up to US$89.8/t and ICI-4 to US$73.2/t, while Newcastle rose to US$145.7/t. Chinese port inventory eased further to 2,279.5 from 2,298.9. Unlike in past weeks where we characterized Indonesian coal as more quota-constrained than demand-constrained, this week's move looks genuinely demand-led: northern Chinese port stocks fell 5.44% w-w to 25.27mt (a 12.1% monthly drawdown), with domestic and import price indices both firming on tight supply and active restocking.
Base metals were mixed.
- LME copper (cash) stood at US$14,359/t as of 3-Sep, nickel at US$16,615/t, and tin at US$54,450/t.
- Brent extended its advance to the mid-US$90s/bbl (intraday spikes toward US$97 reported amid the Iran-Kuwait escalation), a second consecutive weekly gain.
- Gold eased to US$4,434/oz (3-Sep) as the hot NFP reset hike expectations. MHP softened slightly to US$14,587/t from US$14,878/t. Indonesian NPI (Ni 14%) FOB was at US$149.7/mtu.
BRIDS Key Research Reports
United Tractors (UNTR IJ, Buy maintained, TP Rp30,600, Tactical raised to OW) — Stronger 2H26 Momentum with RKAB Revision Tailwinds. July operational data improved, with PAMA coal production up 10% m-m to 13Mt (still -7% y-y) and Komatsu unit sales up 31% m-m to 399 units. RKAB revisions have generally trended upward versus miners' original submissions, and combined with seasonally drier weather should support stronger PAMA volumes into 2H26; UNTR's own coal sales fell 28% m-m on Barito River logistics constraints, a risk management still frames as within historical seasonality but flags as a downside risk if water levels don't improve by Oct-Nov. UNTR trades at 7.7x 12-month forward P/E with domestic funds still 30bps underweight versus JCI, and we continue to prefer it as the cleanest listed proxy for the RKAB-revision theme given DMO policy risk facing coal miners more broadly.
Dian Swastatika Sentosa (DSSA IJ, Not Rated) — A Scalable Data Center Growth Plan, Backed by Deep Connectivity. DSSA targets a 50:50 Energy/non-Energy EBITDA mix by FY28 (from roughly 80:20 today), driven by MORA's FWA/FTTH build-out and SM+'s data center business, with renewables (a 1GW/year solar facility in Kendal and a 440MW geothermal project) to start contributing from FY29. The 21MW SMX01 data center — a 50:50 JV with LG — is set to begin operations in October with Taiwanese GPU-as-a-service provider Konst as anchor tenant on a 3-5 year contract, and can scale to 60MW within roughly a year at a guided 55% EBITDA margin. Net gearing is manageable at 0.7x ND/EBITDA, though FY26F capex of ~US$707mn (plus a potential US$390mn for the SMX01 expansion) is substantial, and the stock already trades at a rich 45.7x LTM PE/39.1x EV/EBITDA.
Post-earnings notes
Bank Rakyat Indonesia (BBRI IJ, Not Rated): 2Q26 net profit Rp15.3tr (-1% q-q, +21% y-y), 1H26 Rp30.9tr (+17% y-y, 53% of FY26F); FY26 loan growth guidance raised to 8-10% from 7-9% on broad-based corporate/commercial growth, though Sept-26 SOE loan repayments from Pertamina Patra Niaga and Agrinas are a 2H26 watch item; trades at 1.5x FY26F PBV, -1.7SD below its 5-year mean.
Indofood Sukses Makmur (INDF IJ, Buy maintained, TP raised to Rp9,200 from Rp9,000): FY26/27F earnings raised 2.1%/4.0% post-1H26 on stronger ICBP, partly offset by softer Bogasari volumes; Bogasari margin ran ahead of guidance on flour price hikes offsetting IDR pressure, while the agribusiness segment is positioned as an El Niño beneficiary on elevated global CPO prices; trades at 5.5x FY26F PE, a 36.3% discount to ICBP.
Week Ahead: Key Catalysts
- BI RDG, 22-23 Sep. Destry Damayanti's first meeting as confirmed Governor; consensus expects a hold at 5.75% consistent with her stability-first messaging.
- Iran-Kuwait escalation. Scope and duration remain the key swing factor for Brent and, by extension, Indonesia's fuel subsidy, inflation and BI policy calculus.
- US CPI/PPI ahead of the 16-Sep FOMC.
- US Labor Day, Mon 7-Sep.
… Read More 20260907 BRIDS Market Pulse