FROM EQUITY RESEARCH DESK
IDEA OF THE DAY
Macro Strategy: The Resistance Test
- Domestic buffers could help defend 7.5% resistance, although external pressures and IDR weakness increase breach risks.
- An October Fed pause offers temporary relief, but persistent inflation risks and further tightening limit its benefits.
- BI's targeted measures support IDR stability and liquidity, but persistent currency pressures favour another 25bps hike.
To see the full version of this report, please click here
To see the full version of this snapshoot, please click here
RESEARCH COMMENTARY
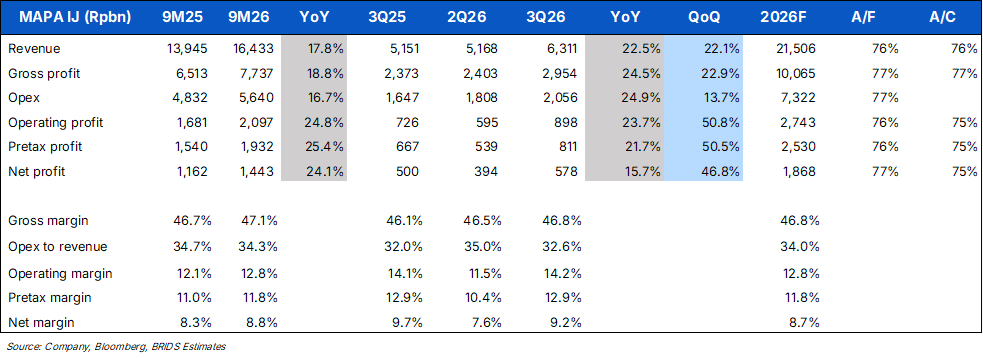
MAPA (Buy, TP Rp800) – Solid Rev & Earnings Growth, In Line
- MAPA reported 9M26 rev growth of 17.8% yoy, while net profit rose solid growth of 24.1% yoy on manageable opex (lower marketing & promotion, svc charge and depreciation exp as % of sales). Both came in line to our FY26 est.
- In 3Q26, rev grew 22.5% yoy (+22.1% qoq), supported by overseas market which grew 61.7% yoy, led by Malaysia (+363% yoy). We believe this is reflecting the increased contribution from Sports Direct, which now Malaysia contributing 10% of rev in 3Q26 (vs. 2% in 2Q26). Both Thailand and Philippines grew 18% and 14%, respectively. Meanwhile, domestic market grew modestly at +11.8% yoy.
- Gross margin expanded 70bps yoy and 30bps qoq to 46.8% in 3Q26 partially supported by the ASP hikes and lesser aggressive promotions. Op margin remained broadly stable at 14.2% and net margin stood at 9.2%. (Christy Halim & Sabela Amalina – BRIDS)
MAPI (Hold, TP Rp1,520) – Robust Rev & Earnings Growth, Broadly In Line
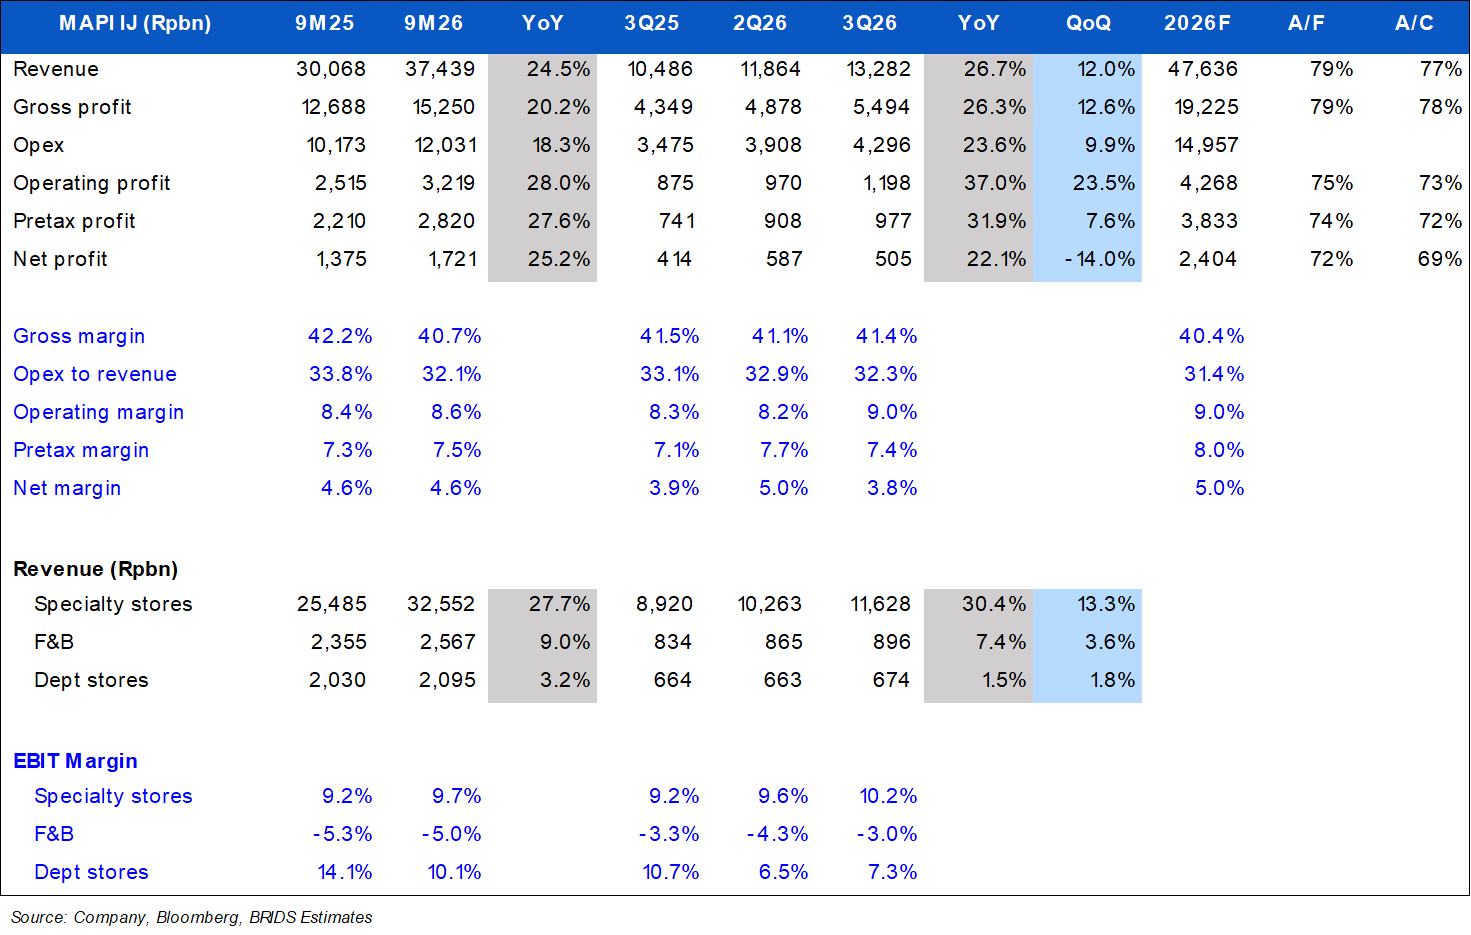
- MAPI booked solid rev and earnings growth of 24.5% and 25.2% yoy in 9M26 – both came broadly in line to ours, while slightly below cons’ on the bottom line.
- In 3Q26, rev grew strongly at 26.7% yoy (+12.0% qoq), driven by the solid performance of specialty stores (+30.4% yoy), particularly Fashion (+41.0% yoy) and Active (+22.5% yoy). F&B remains resilient (+7.4% yoy), while Dept stores recorded modest growth of +1.5% yoy.
- Overseas business grew higher at +58.3% yoy, led by Vietnam (+54.5%) and Thailand (+18.4%). Malaysia also showed improvement in 3Q26, potentially supported by the acquisition of Sports Direct in Jul26. Meanwhile, Domestic rev increased +20.7% yoy in 3Q26.
- On profitability, gross margin remained broadly stable at 41.4% (30bps higher qoq, 10bps lower yoy in 3Q26. Additionally, opex-to-rev declined to 32.3% in 3Q26, which supported op margin expansion to 9%. Christy Halim & Sabela Amalina – BRIDS)
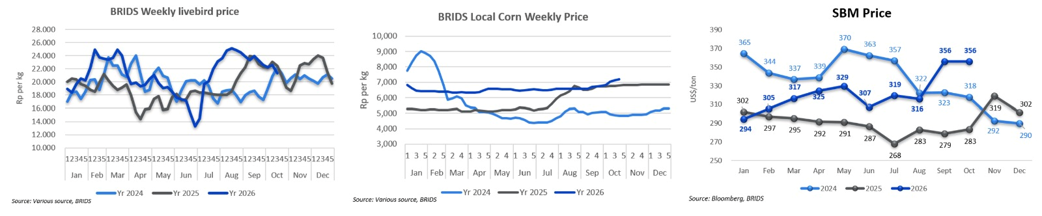
Poultry (Overweight) – 3rd Week of October 2026 Price Update
- LB prices continued their downtrend, reaching Rp19.1k/kg at week-end, with the weekly average down 6% wow to Rp21.3k/kg.
- Local corn prices climbed further to Rp7.2k/kg from Rp7.1k/kg the previous week, marking another high for the year.
- SBM prices continued to ease to US$340/t today, while the Oct-26 MTD average remained higher at US$356/t (flat mom, +26% yoy).
- LB prices have fallen below our estimated breakeven level of ~Rp21.6k/kg, signaling renewed near-term margin pressure for integrators. Meanwhile, corn prices continued to climb to a new YTD high, adding to feed cost pressure, while the recent easing in SBM prices offers limited relief. Overall, integrator margins are under increasing pressure as LB prices sit below breakeven amid persistently elevated feed costs. The impact of the recent culling will only be felt from mid-November at the earliest. (Victor Stefano & Wilastita Sofi – BRIDS)
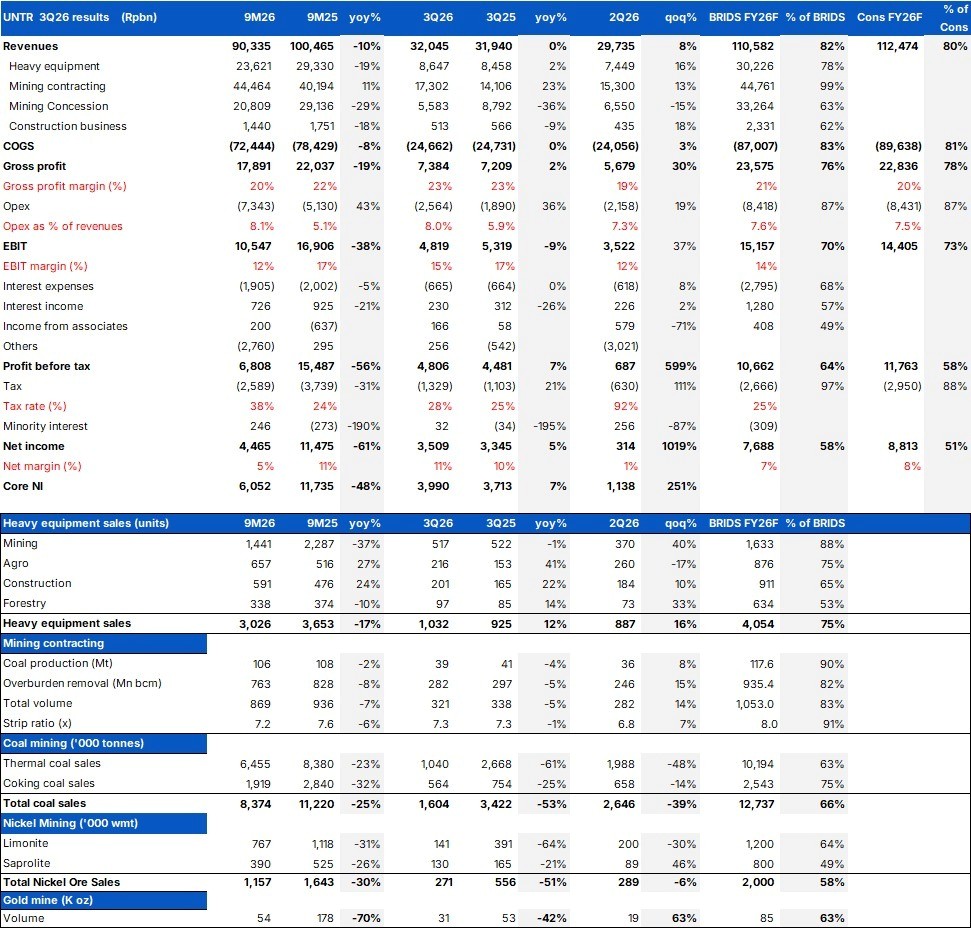
UNTR (Buy, TP Rp30.6k): A strong 3Q26 Earnings Recovery, though 9M26 still lagged
- A strong 3Q26 earnings recovery. UNTR”s 3Q26 core net profit rose to Rp4.0tr (+7% yoy/ +251% qoq), driven by 3Q26 revenue growth of 8% qoq to Rp32.0tr, with GPM improving to 23% from 19% in 2Q26. Despite this, 9M26 earnings still lagged expectations, as net profit of Rp4.5tr (-61% yoy), only reached 58%/51% of our/cons. FY26F. This mainly reflected misses in coal mining sales.
- Heavy equipment sales and mining contracting improved qoq. Komatsu sales rose 16% qoq to 1,032 units, led by mining equipment (+40% qoq), bringing 9M26 sales to 75% of our FY26 forecast. PAMA's coal production and overburden removal rose 8% and 15% qoq, respectively, reaching 90% and 82% of our FY26 forecasts.
- Coal sales affected by prolonged dry seasons, although a 4Q26 catch-up is possible Coal sales fell 39% qoq to 1.6Mt in 3Q26, affected by low Barito river levels during the dry season, bringing 9M26 sales to only 66% of our FY26 forecast. While improved river conditions and higher RKAB approvals could support stronger deliveries in 4Q26, meeting our FY26 forecast would still require 4.4Mt of sales (+172% qoq), suggesting downside risks to our volume assumptions.
- Nickel sales remained weak, while gold continued to recover. Nickel ore sales reached only 58% of our FY26 forecast in 9M26, following a 51% yoy decline in 3Q26. Meanwhile, gold sales increased 63% qoq to 31k oz, supported by the resumption of Martabe operations in May26, although 9M26 sales remained 70% lower yoy. (Erindra Krisnawan, Kafi Ananta, Taufan Fadhillah – BRIDS)
MARKET NEWS
SECTOR
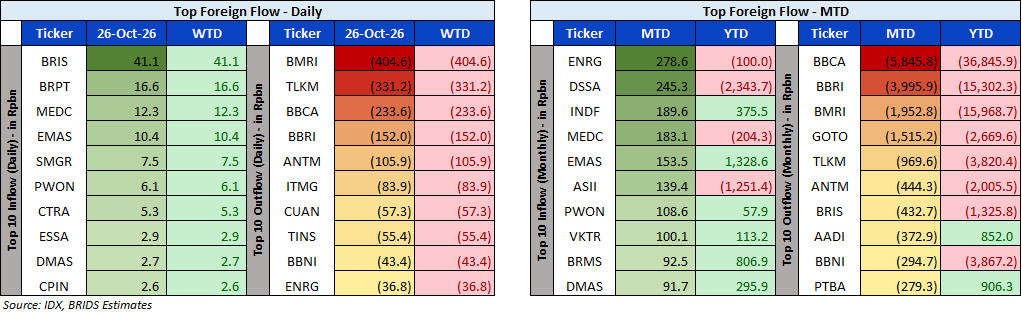
Top Foreign Flow – JCI, October 26, 2026
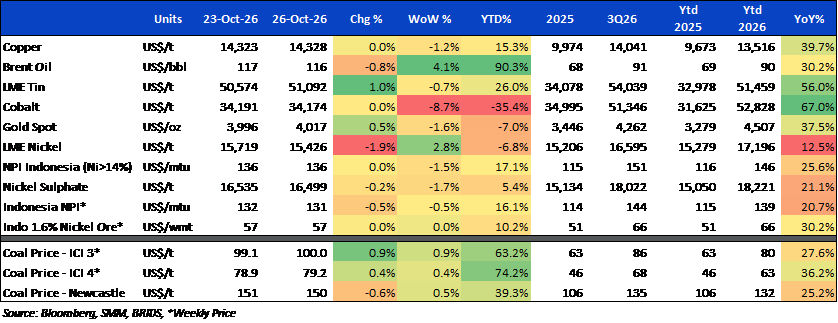
Commodity Price Daily Update October 26, 2026
CORPORATE
BREN Raises Darajat Unit 3 Capacity to 130.55MW
BREN completed the retrofit of Darajat Unit 3, increasing capacity from 122MW to 130.55MW and total installed geothermal capacity to 935.55MW, bringing it closer to its 1GW target by end-2026. The project was completed on schedule and without safety incidents, while BREN and Mitsubishi Power Indonesia will explore further performance and reliability improvements at Darajat Units 2 and 3. (EmitenNews)
BUMI Acquires Australian Exploration Asset for US$22mn
BUMI, through indirect subsidiary PT Bumi Resources Australia, acquired 100% of Mount Margaret Mining Pty Ltd for US$22.0mn, expanding its portfolio beyond coal into exploration assets in Western Australia. Mount Margaret holds 38 exploration licenses covering c.1.23mn hectares, with historical resources including c.52.1mn tonnes of copper-bearing material and c.1.0mn tonnes of gold-bearing material, although the asset remains at exploration stage and will require further development before production. (Bisnis)
KAEF Targets Rp4.18bn Annual Revenue from CMO Business
KAEF is expanding its contract manufacturing organization (CMO) business to manufacture pharmaceutical products for other companies, targeting annual revenue of c.Rp4.18bn from the segment. The company is offering manufacturing capacity across its Jakarta and Bandung facilities, covering products such as tablets, capsules, sterile injections, softgels, herbal products, suppositories, and specialized treatments, as part of efforts to optimize plant utilization and diversify revenue. (Bisnis)
MBSS Secures Five-Year Hauling Agreement for Up to 500kt/Month
MBSS signed a five-year material transportation agreement with PT Global Energi Lestari, targeting hauling volumes of up to 500kt per month. Shipment details, including routes, vessels, schedules, and freight rates, will be determined under separate agreements, while MBSS expects the contract to support long-term volume growth and strengthen its earnings base, although the contract value has not been disclosed. (EmitenNews)
PPRO Reshuffles Board to Support Business Recovery
PPRO reshuffled its board of directors following an Oct 22 EGM, appointing Adi Suryolaksono as Director of Business Management and HCM while Ikhwan Putra Pradhana remains Finance Director. Management said the changes are aimed at strengthening coordination across business, finance, and human resources as PPRO focuses on financial recovery, governance, and improving its operating fundamentals. (Bisnis)
SBMA Strengthens Industrial and Medical Gas Business in Kalimantan
SBMA is expanding its industrial and medical gas business in Kalimantan through operational infrastructure development and a strategic partnership with PT Kaltim Parna Industri (KPI) to strengthen gas supply and distribution. The initiative aims to serve growing demand across mining, energy, manufacturing, construction, and healthcare while supporting long-term growth and operational reliability. (Kontan)