|
FROM EQUITY RESEARCH DESK |
|
|||||||||||
|
IDEA OF THE DAY |
|
|
|
|
|
|
||||||
|
Darma Henwa: Fleet Internalization on Track, Potential New Contracts Offer Further Upside (DEWA.IJ Rp258; BUY TP Rp530) · DEWA’s fleet internalization strategy delivered margin expansion, with 3Q26 EBITDA rising 27.5% qoq and margin reaching 33.0%. · Sebuku underpins volume growth, while potential tender wins could lift FY27F EBITDA by 32.8% under our upside scenario. · Reiterate Buy rating and TP of Rp530 TP on improving operating efficiency and accelerating FY27F earnings. To see the full version of this report, please click here To see the full version of this snapshoot, please click here
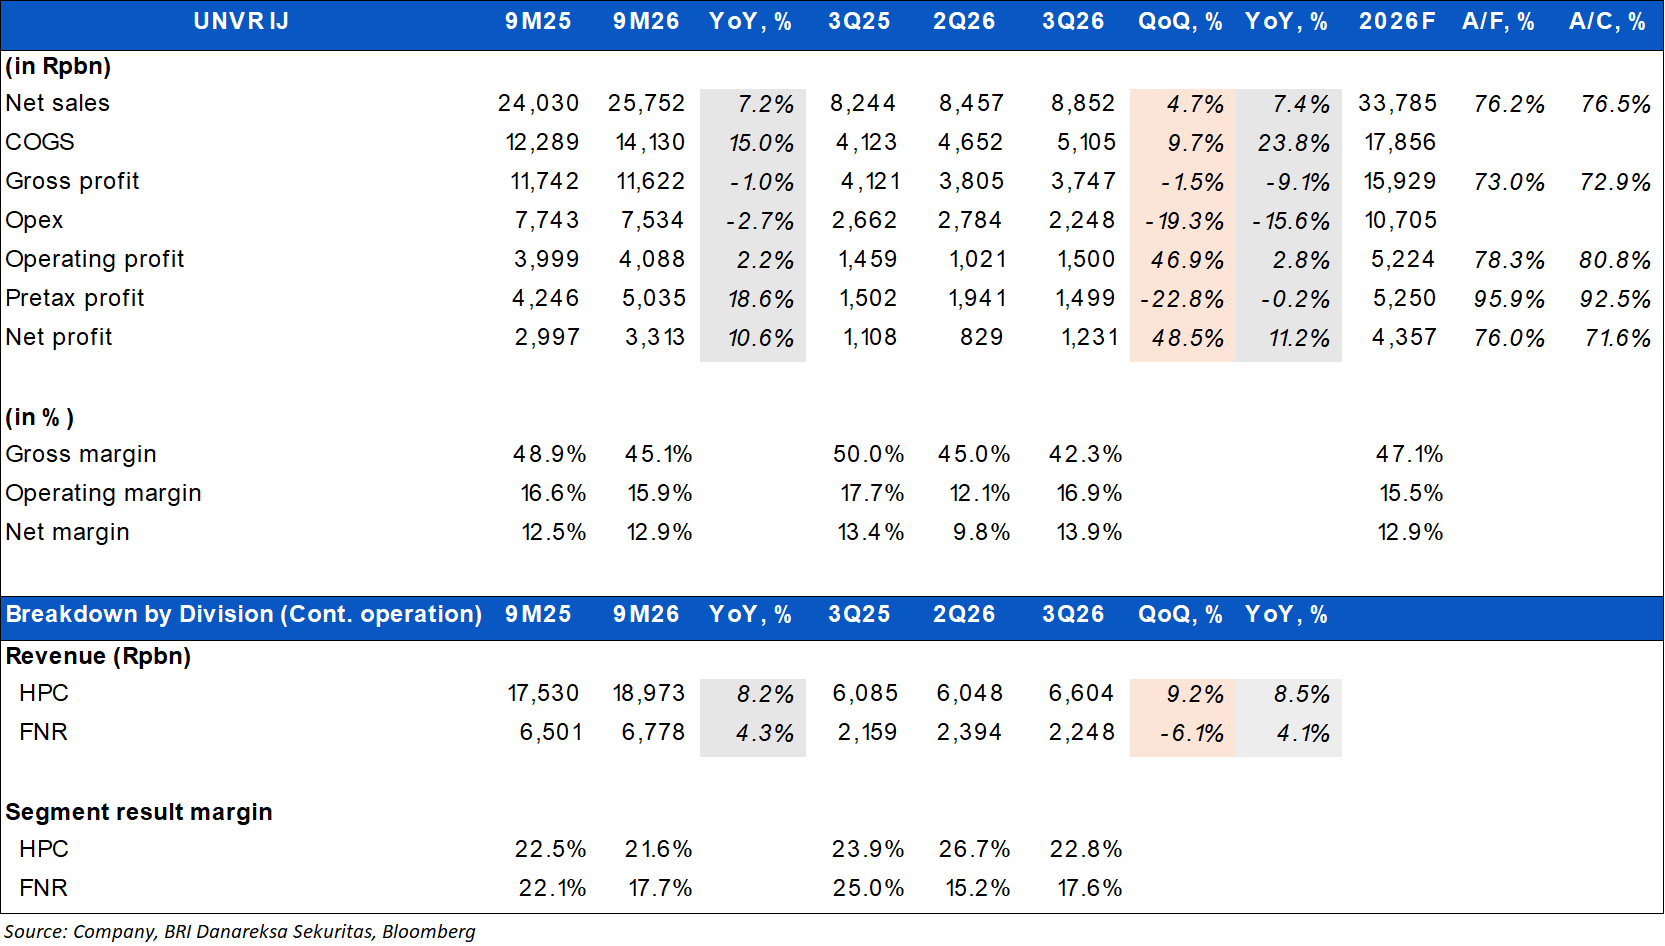
RESEARCH COMMENTARY UNVR (Buy, TP Rp2,200) - 9M26 Result & Earnings Call KTA: Inline with Our Estimates · UNVR reported 9M26 revenue of Rp25.8tr (+7.2% yoy) excluding the contribution sales of Sariwangi. Net profit reached Rp3.3tr (+10.6% yoy), equivalent to 76.0% of our FY26 estimates (i.e., inline). Including Sariwangi, net profit stood at Rp4.2tr (+35.5% yoy). · 3Q26 revenue grew +7.4% yoy/+4.7% qoq to Rp8.9tr, driven by volume growth of 6.4% and ASP growth of 0.9%. By category, Home & Personal Care (HPC) revenue grew 8.5% yoy, supported by volume growth of 8.6%, while Foods & Refreshment (F&R) posted 4.1% domestic rev growth. · Growth was broad-based across channels in 9M26. General Trade (GT) recorded single-digit growth, Modern Trade (MT) delivered mid-single-digit growth, while E-commerce and Health & Beauty (HABA) remained key growth drivers, posting high-double-digit growth. · Gross margin eased to 45.1% in 9M26, reflecting input cost inflation despite selective ASP increases implemented in Aug26. Operating margin declined 70bps yoy to 15.9%, due to higher distribution costs, employee remuneration, service fees, and enterprise technology solution fees. · For the remainder of 2026, mgmt expects volume-led growth and modest margin improvement. Mgmt will continue to monitor Middle East inflationary pressures into 2027 and assess the need for pricing adjustments, cost savings, and investment allocation. FY26 transformation costs are expected to decline 40–50% yoy, with further updates on the Foods business expected before year-end. (Christy Halim & Sabela Amalina – BRIDS)
MARKET NEWS |
||||||||||||
SECTOR
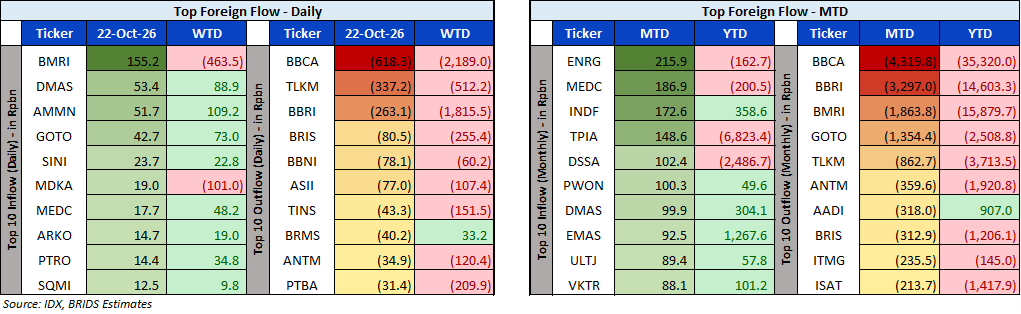
Top Foreign Flow – JCI, October 22, 2026
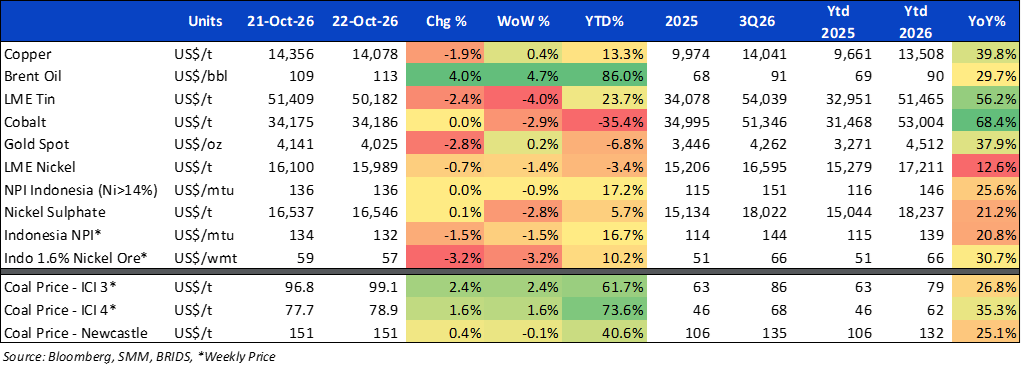
Commodity Price Daily Update October 22, 2026
CORPORATE
AMMN Plans Rp1tr Share Buyback, No AGM Approval Required
AMMN plans a share buyback of up to Rp1tr, including transaction costs, from 22 October 2026 to 22 January 2027. It will repurchase about 266.84mn shares, or 0.37% of issued and paid-up capital, well below the 20% limit under POJK 13/2023. No AGM approval is needed under OJK’s relaxation, and funding comes entirely from internal cash, not IPO proceeds or loans. (Emiten News)
BBRI Launches Rp1tr Phase II Buyback to Fund MESOP
BBRI will conduct a phase II 2026 buyback of up to Rp1tr from 22 October 2026 to 21 January 2027, after OJK approval. Treasury shares, capped at 10% of issued capital, will be used for MESOP after AGM approval. Funded from internal cash, the buyback lowers pro forma total assets to Rp2,341.79tr from Rp2,342.79tr and equity to Rp332.62tr from Rp333.62tr, while net profit stays at Rp31.18tr. (Emiten News)
BNGA Denies Delisting Plan, Commits to Meeting Minimum Free Float Rules
BNGA denied reports of a delisting plan, with CIMB Group stating in a 22 October 2026 press release that it has no privatization plan and no formal decision or proposal on the matter. CIMB Group remains committed to its Indonesian business and will meet all rules, including minimum free float, in a timely and structured manner. Emiten News)
BRMS CEO Buys 5.5mn Shares as Company Targets 3Q26 Net Profit
BRMS President Director Agus Projosasmito bought 5.5mn shares on 22 October 2026, in two transactions of 2.2mn shares at Rp446 and 3.3mn shares at Rp448, totaling about Rp2.46bn. Over the past 18 months, six of eight directors have bought nearly 13mn shares, reflecting confidence in growth prospects. (Warta Ekonomi)
PTPP’s Rp18.2tr Debt Restructuring Agreement Becomes Effective, Tenor up to 15 Years
PTPP’s MRA with Bank Mandiri, BRI, BNI, and BSI covering Rp18.2tr of obligations became effective on 21 October 2026. Tranche A of about Rp13.33tr will be repaid over 15 years via balloon payment at 3.5% interest, while Tranche B of about Rp4.05tr will be repaid in five years via bullet payment from divestment proceeds at 1.0% interest. Tranche C, covering accrued interest, will be paid in installments over 18 months with no additional interest. (Emiten News)
UNSP Establishes New Subsidiary in Vegetable Oil Trading
UNSP established a new subsidiary, PT Bakrie Bhumi Phala, through its unit PT Agrowijaya (AGW) on 20 October 2026, engaged in wholesale trading of vegetable oils and fats. All of its authorized capital has been issued and fully paid up, with UNSP holding 99.5% and AGW 0.5%. The new subsidiary is expected to help expand the business and increase overall revenue. (Emiten News)
TLKM Completes Rp36.54bn Buyback From Shareholders Opposing Subsidiary Spin-Off
TLKM completed a buyback of 15.96mn shares at Rp2,290 per share, worth Rp36.54bn, to fulfill the rights of shareholders who disagreed with the phase two spin-off of part of its wholesale fiber connectivity segment to subsidiary PT Telkom Infrastruktur Indonesia. Payment to entitled shareholders was completed on 20 October 2026, after the deadline for statements of intent to sell ended on 5 October 2026. (Kontan)
TSPC Sets Rp338.24bn Interim Dividend at Rp75 per Share, Payment on 20 November 2026
TSPC will distribute a 2026 interim dividend of Rp75 per share, totaling Rp338.24bn and equal to 43.66% of its 1H26 net profit. The plan was approved by the board of commissioners on 20 October 2026, based on 1H26 net profit attributable to the parent of Rp774.77bn. Cum dividend date for the regular and negotiated markets is 30 October 2026, with payment scheduled for 20 November 2026. (Investor Daily)